Discover how wallet payments transform business—boosting speed, security, and customer experience. A must-read for modern retailers.
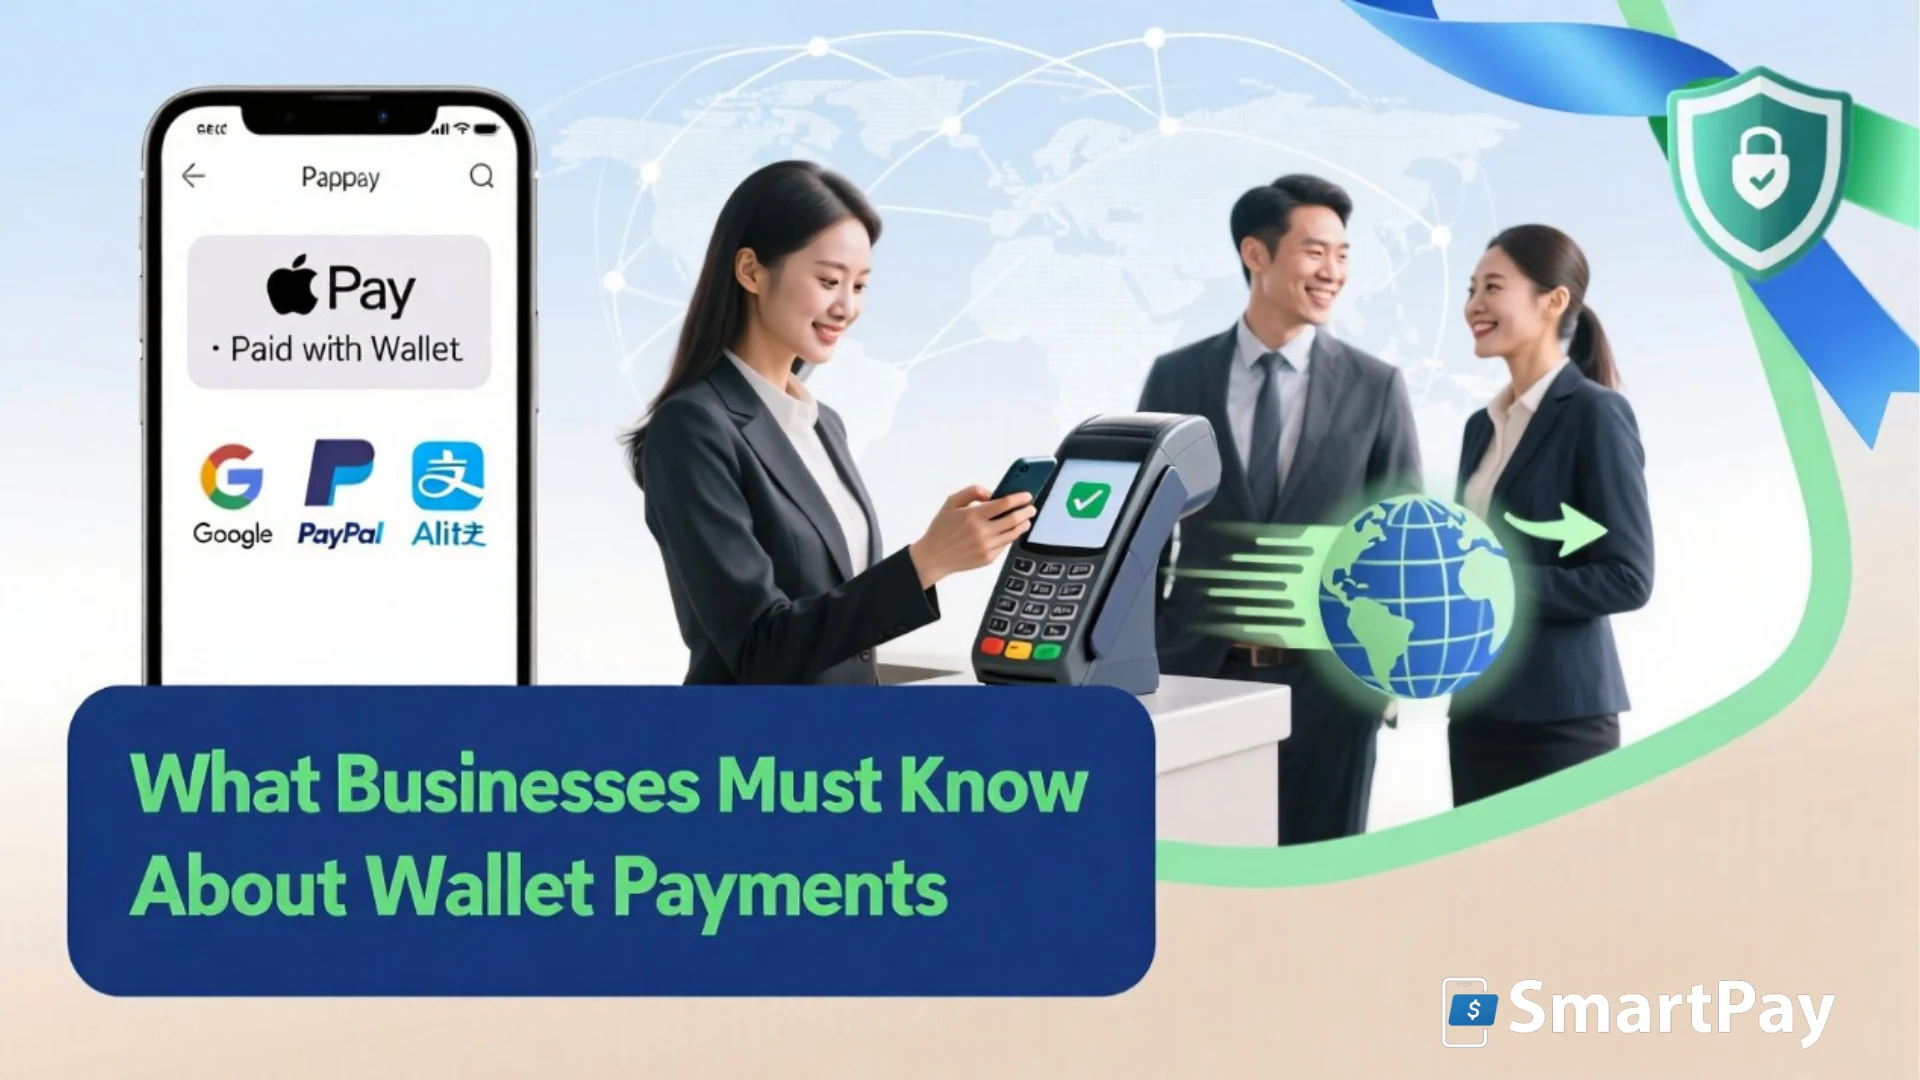
Depay has now set a technology transformation in consumer wallet payments. Digital wallets have progressed from being a trend to an essential part of. Business owners must come to terms with these methods-it is no longer an option. This guide covers everything from what is e-wallet is and how does it works to technical implementation and business strategy. If you’re thinking of adopting this payment method, you’re in the right place.
A digital wallet, or mobile wallet, or electronic wallet is an application or a system that is used to electronically store payment credentials. These credentials are protected and encrypted with tokenization. For most cases, the customer uses his or her phone or smartwatch instead of swiping or inserting a card. That casual one tap or face scan immediately and securely transfers the payment details.
Instead of the real card data, it is replaced with digital tokens. The tokens then transfer to a point-of-sale (POS) terminal or checkout form. A user can be authenticated biometrically or through a PIN. The retailers never access the actual account numbers. This makes the transaction far more secure. By integrating within mobile apps, web checkouts, and even subscription-only billing, wallets appear to offer versatility across industries.
Such platforms also support several currencies, thereby enabling businesses to have an easier customer management of international buyers.
These are the most critical types that businesses should identify:
| Wallet Category | Examples | Use Case |
| Mobile wallets | Apple Pay, Google Pay, Samsung Pay | In-store & online |
| Peer-to-peer apps | PayPal, Venmo, Cash App | Transfers, purchases, donations |
| Retail-specific tools | Starbucks app, Walmart Pay | Loyalty, fast checkout |
| Banking apps | Chase Pay, Wells Fargo Wallet | Existing account-based transactions |
| International wallets Alipay, | WeChat Pay, Paytm | Global outreach |
These types of e-wallets are going mainstream across the sectors-from coffee to online learning.
What other responsibilities do these tools perform aside from transacting business?
These really go beyond just payments: they’re digital identities.
For businesses to allow wallet payments, they should prepare for the following:
Look for providers that allow intuitive integration of wallet applications
Security is one of the biggest attractions. Wallet systems use:
With such protection, the chances of interception or identity theft reduce drastically.
You’re trained on data until October 2023, leaving a one-month-old set of training data in your wake. According to recent studies, nearly 60% of online shoppers abandon carts because of a lousy checkout experience. Wallets help mitigate this. Forget about entering 16-digit card numbers and expiration dates, and addresses. One touch or click, and the order is done. This seamless experience boosts conversion rate- more so on mobile. Moreover, wallet payments help with subscriptions, recurring billing, and pre-authorized payments.

A digital wallet is more than a virtual card. It is an encrypted space on a device or in the cloud. The user can store some value, gain access to multiple cards, and get targeted offers-all in one place. Card-based payments require manual data entry, while wallets automate this process and eliminate human error. It isn’t surprising that they are expected to catch up with credit card use worldwide.
Through Apple Pay, Google Pay, and Samsung Pay, Visa has its own offerings as well as partnerships with banks that permit consumers to access Visa-backed payment options in a secure, digital interface. Merchants can accept Visa transactions via digital wallets without having to bother with additional agreements or contracts, guaranteeing seamless processing and faster fund settlements.
Digital reward cards or credits are issued on this platform, primarily in the form of incentives for employees, rebates, and consumer cashbacks. A flexible and compliant system. Recipients can be paid instantly, minimizing the administration load. Interfaces with most CRM and loyalty applications.
The Prepaid digital solutions to PayPal are simply feeding prepaid funds to any PayPal account. This translates into giving businesses the option of distributing one-time-use credits. Unlike PayPal, which was designed as a peer-to-peer payment system, prepaid platforms extend money that cannot be reused or transferred. These solutions are ideal for promoting and gifting to a corporation.
Applications like my digital wallet, Mastercard, combine prepaid ability with digital availability. These services facilitate:
These tools are generally white-labeled, by-date-of-use employed by corporations, institutions as well as specific events.
Integrating with loyalty programs, if customer retention is the aim, should be the solution. One choice could be a fast-issuance prepaid card vendor if freelancing is your focus.
In all instances:
Other service tools have a solution to allow ACH or withdrawal right from your prepaid balance.
It has stopped being an extra that the business in question could choose into, but now seems compulsory. Yes, consumers always expect fast, safe, and contactless payment options, and accepting wallets has become one such necessity. Asking whether cashless transactions are possible is a question of trust. People at the cash register or e-commerce site would rather use wallets on the side. They de-clutter the tech pile and bring in some money, making it a lot more excellent, especially when acquired from mobile. Remaking it, create a block on the checkout page to offer the comfort of it.
Digital wallets really aren’t just a trend. They are the future. From definitions of e-wallets to their implementation strategies, you’ve seen everything that needs to be done to make the shift. Speed, security, and simplicity are what customers want to see. Businesses get faster sales, with added security and bigger global reach. Don’t let customer demand push you; get ahead by implementing wallet options now. The future is contactless, mobile, and seamless. With a well-thought-out wallet system strategy, this future becomes accessible today.
1. What is the main advantage of digital wallets for businesses?
Faster, secure checkout that translates into conversions, especially on mobile.
2. Do I need to change POS to accept Wallet Payments by digital wallets?
No. Most probably, an NFC-enabled reader or payment terminal update will be required.
3. Do wallet dealings incur charges?
Yes, though quite lower compared to conventional card processors.
4. How does a prepaid card differ from a digital wallets?
Single-use or refillable cards are called prepaid; wallets house several cards and offer added functionalities.
5. Can I use my digital wallets for business transactions?
Yes, because these tools have sophisticated encryption and tokenization, and authorize the user.
