discover-the-hidden-opportunities-in-the-Payments Space Forgot-that-businesses-often-overlook-learn-how-to-optimize-revenue-and-modernize-transactions
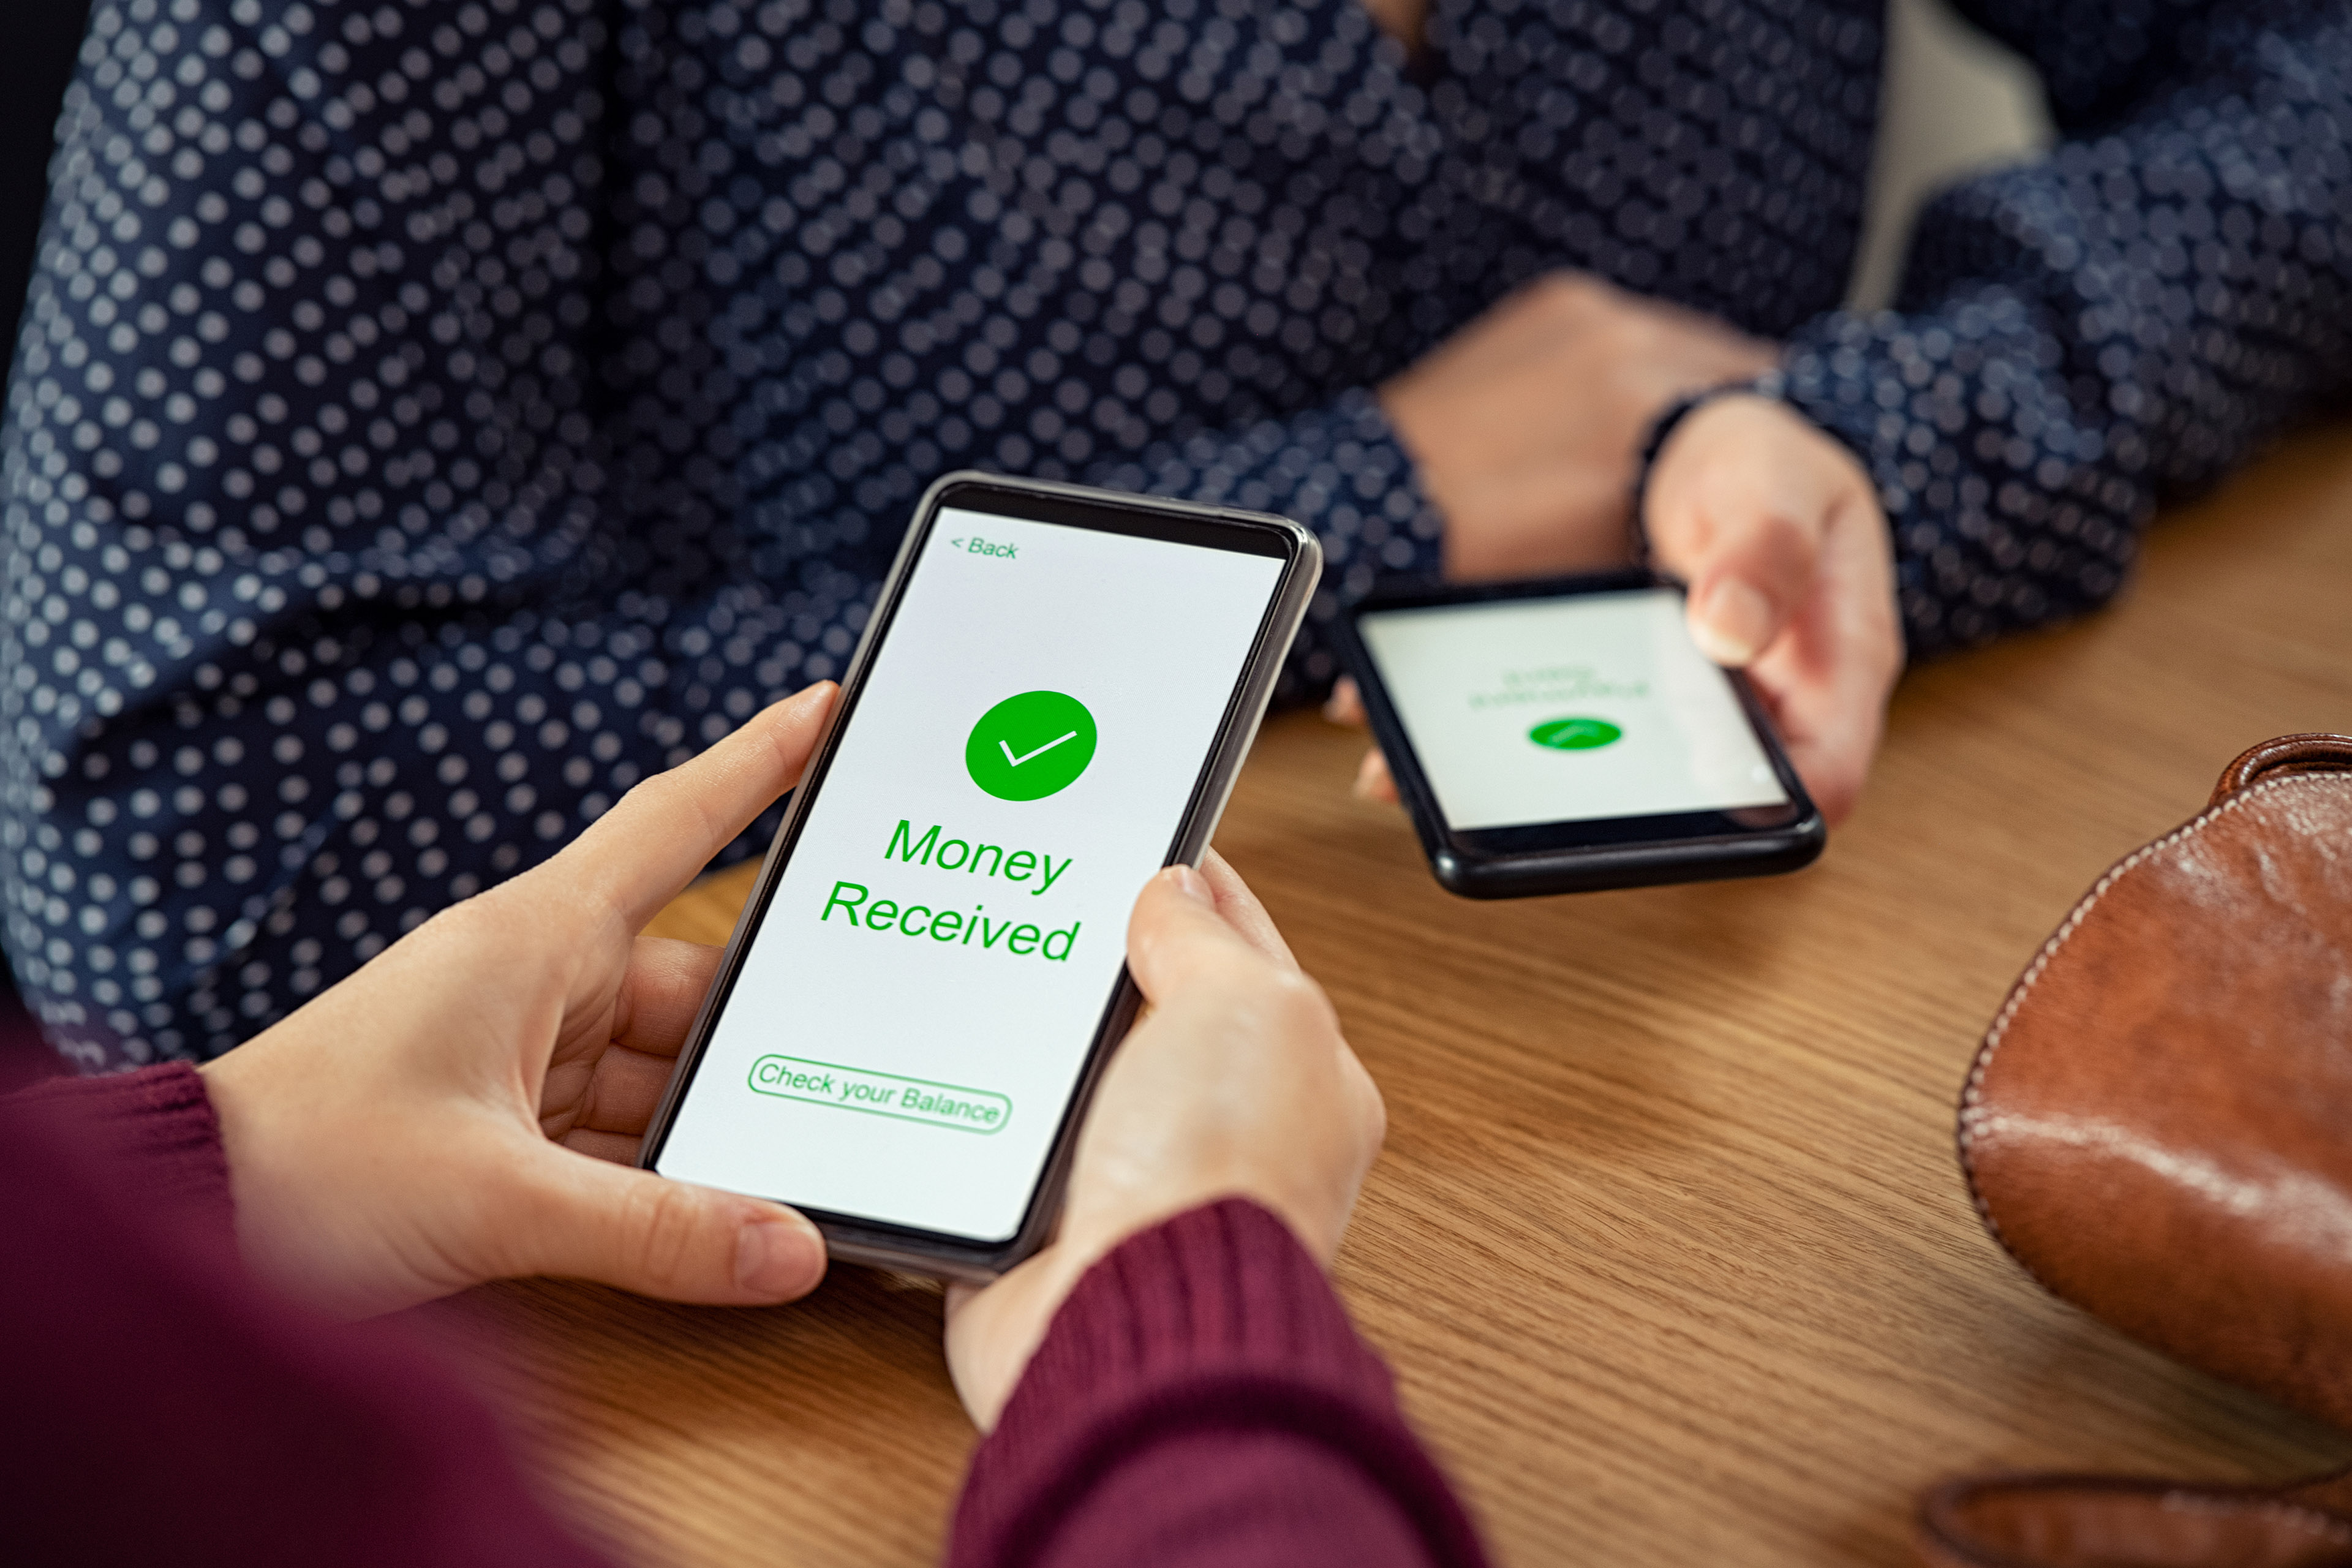
You are either a small business, a startup, or even a giant retailer, and this payment system could be raiding a significant part of your profits. Knowing what lies in fine print is important in managing operations, cutting costs, and staying competitive.
However much you may be aware of what you pay to accept credit cards or digital wallets, the reality is that most such statements are not as clear as they seem. Let us see some of the major cost areas that are easy to overlook, but are tough on your bottom line.
Many providers advertise a simple rate-like 2.9% + 30¢ per transaction. But hidden charges are never so straightforward. A lot of fees like PCI compliance, batch settlement, and regulatory charges are sneaked in. Thus, businesses unknowingly pay much higher amounts than they had planned.
Some expenses are not even mentioned during the onboarding phase. Examples include early termination fees, penalties for minimum monthly payments, and late charges for non-EMV card usage. Most probably, the deduction will be noticed long after various deductions have steadily come off the revenue.
A key issue in the field is the lack of clarity in the billing. Terms like “qualified,” “non-qualified,” or “downgraded” rates confuse most people. With no full transparency, understanding the extent to which you are really paying in terms of transactions becomes nearly impossible.
What most merchants believe regarding payments is not actually true. Such misconceptions make it easy for the providers to overprice or upsell services that are not even necessary.
Some of the common myths are:
These are outdated misconceptions. Actual cost often depends on what type of card is being processed, the volume of transactions, and margins from the processing companies.
The world is witnessing improved transaction efficiency, depending on your source for this supposed knowledge.
Pricing models such as interchange-plus with no hidden markups, transparent flat-rate models, or membership-based systems give you more control. Some providers offer even real-time reporting dashboards, contract-free accounts, and better integration into accounting software.
With every credit and debit card purchase made by your customers, you will have an entire chain of service providers being paid, such as card networks, processors, banks, and so on.
You may be charged with:
These fees are the kind of things you are never told upfront, and they could rack up in no time, especially if you have online or international customers.
It wouldn’t be just Visa or MasterCard. The payment world rages with different methods, some more expensive than others.
Digital wallets (such as Apple’s Apple Pay, Google’s Google Pay), crypto payment, business credit cards, and a set of premium rewards cards almost always have higher interchange rates or network fees. If your provider never states what you’re accepting, you may just be getting an extra charge hiddenly.
There are so many difficult terms and archaic practices, not to mention the absence of standardization in the payments industry. Technology has advanced so fast that policy has failed to catch up.
What else?
Leaving space for confusion, unfair pricing, and exploitation would be especially open to small businesses without negotiation clout.
|
What you expect |
What usually happens |
|
Fixed rate pricing- for the flat rate |
added up additional charges and backend fees |
|
There are no monthly fees. |
However, standard minimum charges do apply. |
|
Free equipment: |
hidden long-term lease in the contract |
|
One simple rate, |
But Tier pricing differs depending on the card type. |
|
Transparent reports, |
ambiguous statements or coded line items. |
You want to stay under the dark cover of not knowing. Here is how to keep your business free from hidden charges and unfair terms:

Don’t ignore those long and boring billing reports. Those small, unexplained charges become big losses in the long run when they are repeated.
If your processor can’t give you layman’s terms to explain your fees, it’s a bad sign. Then ask for a “true effective rate” – the real cost after all fees.
Ask and always negotiate for better terms. Compare many processors before you sign. Push, and many of them will match or beat competitor pricing.
They can appear simple; flat-rate models can get very expensive at scale. Interchange-plus is a good option where you get the actual cost passed on to you, along with the full breakdown.
If your current payment partner does not get you clarity or tracks that help you monitor expenses, it’s time to change.
Simplicity, honesty, and clarity have long been forgotten by the payments space. It is alienating between invisible costs, obsolete systems, and intimidatingly complicated billing.
Everything from forgotten payment fees and merchant fees transparency issues to hidden charges in card payments and, for some organizations, concerning payment methods not recognized by the organization, businesses lose money without them even knowing their costs. There is a gap that requires closing in the payments industry-the first step is awareness.
If you learn the secret costs of payment processing and break through payment processing myths and explore overlooked payment options, well, control and increase your margins will belong to you.
Extra charges like PCI compliance, cross-border fees, AVS charges, and downgrade fees. They sneak in mostly unannounced into your monthly statements.
Ask them what your effective rate is–total fees divided by total transaction volume. If over 3.5%, chances are you are being charged more.
Not necessarily. They are nice for simplicity, but may cost more for some high-volume merchants. Interchange-plus models seem under consideration in terms of optimal long-term value.
Lack of regulations and standardization in the industry lets the providers hide their fees in convoluted bills. Payment Methods just skim through their contracts, which processors rely on.
No long-term contracts, easy-to-read statements, low fees,Payment Methods integration, real-time reporting, and friendly support.
