Merchant Accounts vs Payment Gateways explained. Learn the role of your payment processer in a complete payment solution.
If you’re setting up the ability to accept credit cards or digital payments, you’ll quickly encounter two essential terms: Merchant Accounts and Payment Gateways. They are often mentioned together, sometimes even used interchangeably, which can create confusion for business owners trying to choose the right payment solution.
The truth is that both play very different — but equally important — roles in the payment process. Understanding how they work, how they interact, and how a payment processer ties everything together will help you build a reliable, secure, and cost-effective system for accepting payments.
Let’s break it down in simple terms.
A merchant account is a special type of bank account that allows your business to accept card payments. When a customer pays with a credit or debit card, the funds don’t go directly into your business checking account. Instead, they are first deposited into the merchant account. Think of it as a temporary holding place. After the transaction is approved and settled, the money is transferred from the merchant account into your regular bank account, usually within one to three business days.
Merchant accounts are responsible for:
Without merchant accounts, businesses would not be able to legally or technically accept card payments.
Merchant accounts are typically provided by banks or underwriting institutions, often through a payment processer or integrated payment solution provider.
Approval usually requires underwriting. Providers may review your:
High-risk industries may face higher fees or stricter terms.
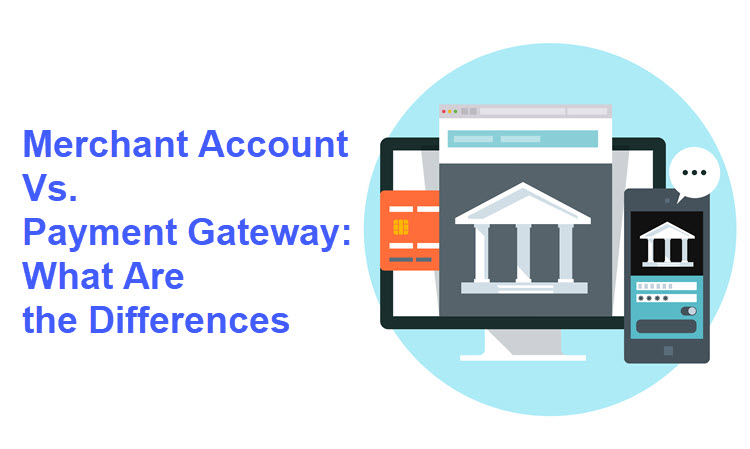
While merchant accounts hold the money, payment gateways handle the communication.
A payment gateway is the technology that securely captures a customer’s card information and sends it for authorization. It acts like the digital bridge between your checkout page, the payment processer, the card networks, and the bank.
If you accept payments online, the gateway is what encrypts and transmits the data safely.
Payment gateways typically:
Without payment gateways, online payments simply wouldn’t be possible.
You interact with gateways whenever a customer:
Here’s an easy analogy:
The gateway sends the transaction information.
The merchant account receives and temporarily holds the money.
Both are required for a complete payment solution.
Let’s walk through what happens when a customer makes a purchase online.
All of this happens within seconds.
A payment processer is the company that manages the transaction flow between the gateway, card networks, and banks.
They:
Some providers bundle processing, merchant accounts, and payment gateways into one platform. Others allow you to choose separate vendors.
In most cases, yes.
If you want to accept credit or debit cards, a full payment solution usually includes:
A merchant account
A payment gateway
A payment processer
However, many modern providers package them together, so you might not realize you’re using all three.
For example, Stripe or Square combine these services into one simplified offering.
You might get:
This can sometimes reduce fees but may require more management.
One provider supplies everything:
This is easier to manage, faster to set up, and often ideal for small to mid-sized businesses.
Understanding pricing helps you avoid surprises.
Some all-in-one payment solution providers combine everything into a single rate.
Both components are critical for protecting customer data.
A strong payment processer coordinates these protections.
It’s not a matter of one being more important than the other. You can’t process payments without both.
If the gateway fails → data can’t be transmitted.
If the merchant account fails → funds can’t be received.
Your business needs a reliable combination.
Many providers advertise a single payment solution, so merchants assume it’s just one system. Behind the scenes, multiple services are still operating.
The simplification is good for usability, but understanding the structure helps when:
When evaluating options, prioritize providers that offer:
Whether bundled or separate, your merchant accounts, payment gateways, and payment processer should work seamlessly.
Often prefer all-in-one systems because they are:
May choose specialized gateways or dedicated merchant accounts to optimize rates and customize risk management.
If you plan to sell globally, your payment solution should support:
Not every gateway or merchant provider can handle this efficiently.
The line between merchant accounts and payment gateways is becoming less visible as platforms merge services. Still, the fundamental roles remain the same.
We’re also seeing growth in:
Choosing a flexible payment processer ensures you can adapt.
Understanding the difference between Merchant Accounts and Payment Gateways empowers you to make smarter decisions about your payment infrastructure.
To recap:
